

Returns shown in USD. Price source: Tiingo.
What is Credo's risk, return, and volatility like?
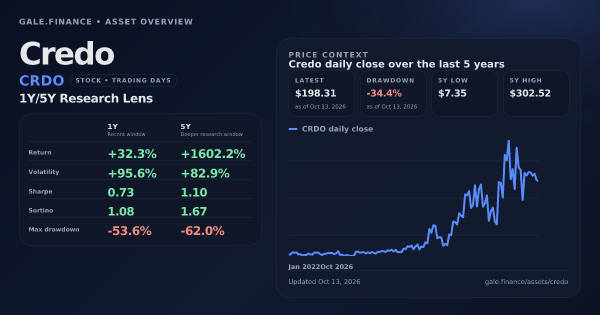
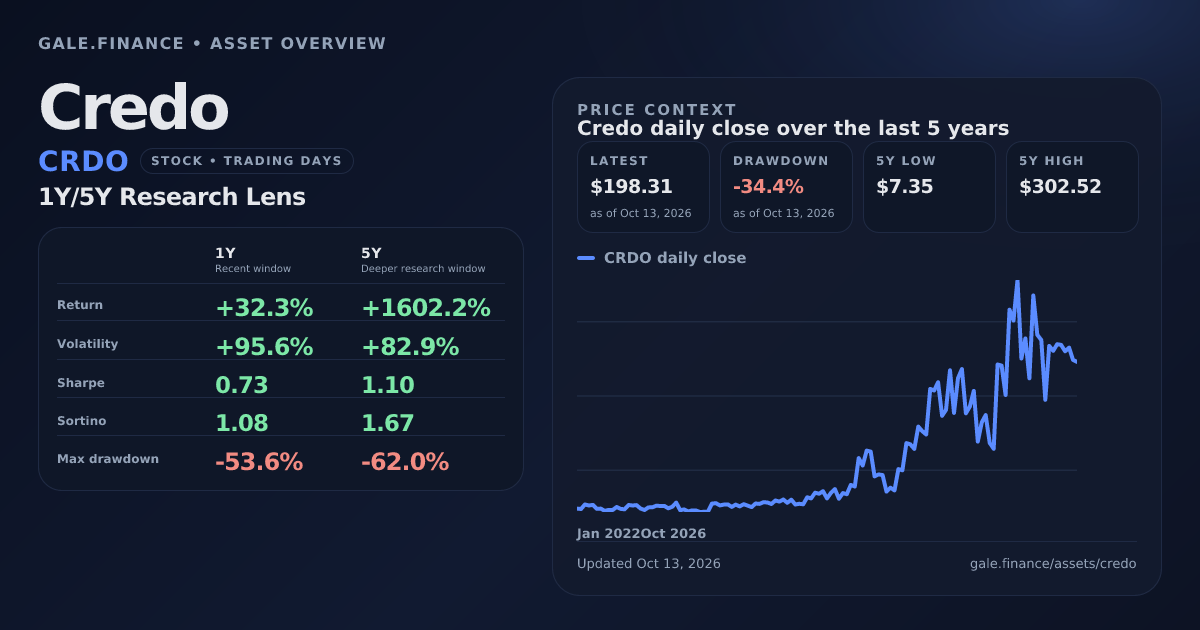
Credo returned +32.3% over the 1Y window. On the 5Y lens, Sharpe ratio is 1.10, annualized volatility is 82.9%, and max drawdown is -62.0%.
Cite This Comparison
"Credo (CRDO): Returns, Risk & Drawdowns." Gale Finance, October 13, 2026. https://www.gale.finance/assets/credo/ Free to use with attribution. Please link back to this page or gale.finance.
Trade CRDO
Access this asset on trusted platforms.
Compare this asset against another in Gale Compare Lab
Price history
Credo price over the past 5Y
Track Credo's standalone price path with macro and asset-specific events enabled by default.
Credo price over the past 5Y
Key takeaways
- Total Return: CRDO returned +32.3% over the 1Y window and +1602.2% over the 5Y window ; annualized return over 5Y was +82.6%.
- Risk-adjusted return: Sharpe was 1.10 and Sortino was 1.67 over 5Y. Sharpe counts total volatility; Sortino focuses on downside volatility.
- Volatility & drawdown: Annualized volatility was 95.6% over 1Y and 82.9% over 5Y ; max drawdown was -53.6% over 1Y and -62.0% over 5Y .
- Tail risk (Expected Shortfall): Over 5Y, daily VaR (5%) was -7.5% and Expected Shortfall was -11.7%. VaR is the cutoff; Expected Shortfall is the average move inside the worst 5% of daily returns.
- Skew & kurtosis: Over 5Y, skew was -1.32 and excess kurtosis was 22.06. Skew shows return asymmetry; excess kurtosis shows how fat the tails were versus a Normal distribution.
- Risk ratios: Sortino Ratio: 1.67 , Calmar Ratio: 1.33 , Sterling Ratio: 2.62 , Treynor Ratio: 0.42 , Ulcer Index: 25.56% .
Credo Drawdown
Max drawdown shows the deepest peak-to-trough decline Credo suffered in each research window. 1Y: -53.6%; 5Y: -62.0%.
Credo is currently -34.4% below its prior peak, with the high-water mark at $302.52. 5Y low is $7.35.
5Y drawdown episodes
Credo Volatility
Volatility Credo's annualized volatility shows how widely daily closes moved over 1Y and 5Y. Higher values mean a noisier path, not automatically a better or worse investment. 1Y: 95.6%; 5Y: 82.9%.
Benchmark context
Where CRDO fits relative to other lenses
Benchmark links are secondary on this page. Use them when you want to place the asset against a specific market, factor, or historical counterpart.
Default benchmark
S&P 500
Broad equity benchmark

Nasdaq 100
Growth and tech benchmark
Bitcoin
Cross-asset crypto benchmark
Gold
Store-of-value benchmark
Risk-adjusted ratios
These ratios compare return against different definitions of risk: total volatility, downside volatility, drawdowns, benchmark beta, and time spent underwater.
Credo Sharpe Ratio
CRDO Sharpe Ratio (5Y)
Return per total volatilityThe dot sits at (Credo's annualized volatility, its excess annualized return). The slope from the origin to the dot is the Sharpe ratio — steeper means the asset converted risk into return more efficiently.
Sharpe ratio Credo's Sharpe ratio measures excess return per unit of total volatility. Higher readings mean the asset converted risk into return more efficiently over the same window. 1Y: 0.73; 5Y: 1.10.
A Sharpe above 1.0 is generally considered good, above 2.0 is excellent. Negative Sharpe means the asset underperformed the risk-free rate. Calculated on each asset's full 365-day lookback of available prices and annualized using the asset calendar (365 for crypto, 252 trading days for equities/ETFs/metals).
Credo Sortino Ratio
CRDO Sortino Ratio (5Y)
Return per downside volatilityCredo's daily-return distribution over the long window. Days left of the target line are the only ones Sortino penalizes in the denominator — so a distribution with a fat left tail produces a smaller Sortino even at the same mean return.
Sortino ratio Credo's Sortino ratio isolates downside volatility instead of all volatility. It is the cleaner lens when you care more about bad downside moves than upside noise. 1Y: 1.08; 5Y: 1.67.
A higher Sortino is better. It's useful when upside volatility is common (crypto is the obvious example). Calculated on each asset's full 365-day lookback of available prices, using the daily risk-free rate as the target return, and annualized using the asset calendar (365 for crypto, 252 trading days for equities/ETFs/metals).
Credo Calmar Ratio
CRDO Calmar Ratio (5Y)
CAGR per worst drawdownCredo's CAGR bar sits above zero, the max drawdown bar sits below. Calmar is the ratio of those two magnitudes — a shallow drawdown bar with a tall CAGR bar produces a strong Calmar.
Calmar ratio Credo's Calmar ratio measures return per unit of max drawdown. It is useful when the path of losses matters as much as the final return. 1Y: 0.60; 5Y: 1.33.
Calmar is computed on each asset's full 365-day lookback and uses the max drawdown over that same window.
Credo Sterling Ratio
CRDO Sterling Ratio (5Y)
Return per average drawdownThe underwater curve shows Credo's drawdowns over the long window. Sterling averages every event deeper than the 10% threshold instead of taking only the worst one — so an asset with many mid-size drawdowns scores worse here than on Calmar.
Sterling ratio Credo's Sterling ratio compares return against deep drawdown pressure. It gives a harsher read on assets that compound well but suffer ugly declines along the way. 1Y: 1.00; 5Y: 2.62.
Sterling uses average drawdown events deeper than 10% and subtracts the risk-free rate to report excess return.
Credo Ulcer Index
CRDO Ulcer Index (5Y)
Drawdown painThe underwater curve shows how deep and how long Credo's drawdowns were. Ulcer is the root-mean-square of that curve — both depth and persistence count, so lower is better.
Ulcer Index Credo's Ulcer Index measures both the depth and persistence of drawdowns. Lower is better because it means fewer and shallower underwater periods. 1Y: 27.23; 5Y: 25.56.
Ulcer Index is computed from each asset's drawdown series over the full lookback window.
Credo Treynor Ratio
CRDO Treynor Ratio (5Y)
Excess return per beta vs SPYThe line's slope is Credo's beta to SPY — steeper means more market-sensitive. Treynor divides excess return by that slope, so an asset can look efficient with a shallow beta and a small return, or inefficient with a steep beta and a big return.
Treynor ratio measures excess return per unit of market beta versus SPY. A high Treynor means the asset compensated its market exposure well over this window. A low or negative Treynor means the asset's market risk wasn't rewarded.
Treynor uses beta vs the S&P 500 (SPY) on shared dates and the average 3-month Treasury rate as the risk-free rate.
Credo Tail Risk
Tail-risk stats use daily return distributions rather than simple end-point returns. They show how ugly the left tail has been, how severe the worst 5% of days were, and whether returns were skewed toward outsized upside or downside shocks.
The histogram shows the shape of Credo's daily log returns over the 5Y window. Bars left of the 5% VaR marker are the worst 5% of days; the ES marker is the average loss inside that tail. Skew and excess kurtosis describe whether the distribution is symmetric around zero and whether extreme days are more common than a Normal distribution predicts.
CRDO daily return distribution (5Y)
CRDO daily return distribution (5Y)Log-return histogram with Value-at-Risk and Expected Shortfall markers at the 5% left tail.
| Metric | 1Y | 5Y |
|---|---|---|
| VaR (5%) | -9.5% Historical daily threshold | -7.5% Historical daily threshold |
| Expected shortfall (5%) | -12.7% Beyond the VaR threshold | -11.7% Beyond the VaR threshold |
| Skew | -0.19 | -1.32 |
| Excess kurtosis | 0.27 | 22.06 |
Less negative daily VaR and Expected Shortfall values mean the left tail was less violent. Skew and excess kurtosis help distinguish between steady compounding and a path dominated by occasional extreme moves.
Full stats table
Every window-consistent research metric
Each column keeps the same horizon across returns, ratios, drawdowns, and tail-risk metrics.
| Metric | 1Y Recent window | 5Y Deeper research window |
|---|---|---|
| Total return | +32.3% | +1602.2% |
| Annualized return | +32.3% | +82.6% |
| Volatility | 95.6% Annualized daily closes | 82.9% Annualized daily closes |
| Sharpe ratio | 0.73 | 1.10 |
| Sortino ratio | 1.08 | 1.67 |
| Calmar ratio | 0.60 | 1.33 |
| Sterling ratio | 1.00 | 2.62 |
| Ulcer Index | 27.23 | 25.56 |
| Max drawdown | -53.6% 2025-12-03 to 2026-03-30 | -62.0% 2023-02-14 to 2023-05-04 |
| VaR (5%) | -9.5% Historical daily threshold | -7.5% Historical daily threshold |
| Expected shortfall (5%) | -12.7% Beyond the VaR threshold | -11.7% Beyond the VaR threshold |
| Skew | -0.19 | -1.32 |
| Excess kurtosis | 0.27 | 22.06 |
What viewers usually ask next
What is Credo's 5Y CAGR?
Credo's 5y cagr is +82.6% on Gale using the past 5 years.
What is Credo's 1-year volatility?
Annualized volatility is 95.6% over the past year.
What is Credo's 5-year Sharpe ratio?
Credo's Sharpe ratio is 1.10 using the past 5 years.
What is Credo's 5-year Sortino ratio?
Credo's Sortino ratio is 1.67 using the past 5 years.
What is Credo's 5-year Calmar ratio?
Credo's Calmar ratio is 1.33 using the past 5 years.
What is Credo's 5-year Sterling ratio?
Credo's Sterling ratio is 2.62 using the past 5 years.
What is Credo's 5-year Ulcer Index?
Credo's Ulcer Index is 25.56 using the past 5 years. Lower is better because it means shallower and less persistent drawdowns.
What is Credo's 5-year max drawdown?
Max drawdown is -62.0% over the past 5 years from 2023-02-14 to 2023-05-04.
What is Credo's 5-year daily Value at Risk?
Using historical daily returns, Gale estimates a 5% Value at Risk of -7.48% over the past 5 years.
What is Credo's 5-year Expected Shortfall?
Expected Shortfall is -11.69% over the past 5 years, which captures the average outcome inside the worst 5% of daily returns.
Is Credo still below its all-time high?
Current drawdown is -34.4% versus the all-time high of $302.52 reached on 2026-06-22.
Which benchmark should viewers open first for Credo?
S&P 500 is the default benchmark lens on Gale because it gives the cleanest context for Credo's recent behavior.