

Returns shown in USD.
Which is a better investment: COIN or MSTR?
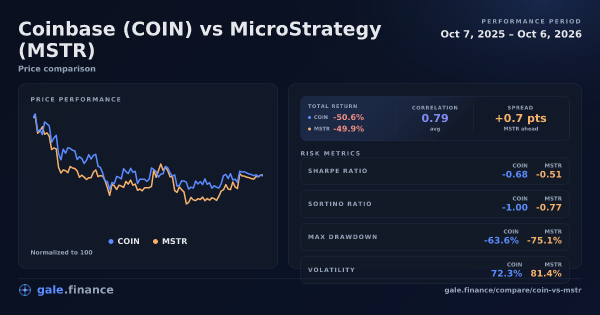
Over the past year, MSTR outperformed COIN. MSTR returned -49.9% compared with COIN’s -50.6%. MSTR had the better risk-adjusted return, with a Sharpe ratio of -0.51 versus COIN’s -0.68. COIN was less volatile than MSTR, and COIN had a smaller max drawdown than MSTR.
Metric winners: Total Return: MSTR; Sharpe Ratio: MSTR; Annualized Volatility: COIN (less volatile); Max Drawdown: COIN (smaller drawdown).
Cite This Comparison
"Coinbase vs MicroStrategy (COIN vs MSTR): Returns, Risk & Volatility (2026)." Gale Finance, October 7, 2026. https://www.gale.finance/compare/coin-vs-mstr/ Free to use with attribution. Please link back to this page or gale.finance.
Relative Performance of COIN vs MSTR (Normalized to 100)
Normalized to 100 at start date for comparison
Trade COIN or MSTR
Access these assets on trusted platforms.
Key Takeaways
- Total Return: COIN delivered a -50.6% total return, while MSTR returned -49.9% over the same period. MSTR outperformed on total returns.
- Risk-Adjusted Return (Sharpe Ratio): Both Sharpe ratios were negative (MSTR -0.51 vs COIN -0.68), meaning both underperformed the risk-free rate; MSTR was less negative.
- Volatility (Annualized): MSTR was more volatile, with 81.4% annualized volatility, versus 72.3% for COIN.
- Maximum Drawdown: COIN's maximum drawdown was -63.6%, while MSTR experienced a deeper drawdown of -75.1%.
- Tail Risk (VaR & Expected Shortfall): At the 5% level (daily log returns), COIN's VaR was -7.32% and its Expected Shortfall (CVaR) was -8.94%; MSTR's were -7.26% and -9.50%. VaR is the cutoff; Expected Shortfall is the average move on the worst days.
- Skew & Kurtosis: Skew: COIN 0.39 vs MSTR 0.58. Excess kurtosis: COIN 0.78 vs MSTR 2.07. Negative skew leans downside; higher excess kurtosis means fatter tails.
- Tail Days & Extremes: 2σ tail days (down/up): COIN 4/10, MSTR 1/8. Worst day: COIN -13.34% (2026-02-05) vs MSTR -17.12% (2026-02-05). Best day: COIN +16.46% (2026-02-13) vs MSTR +26.11% (2026-02-06).
- Risk ratios: Sortino - COIN: -1.00 vs. MSTR: -0.77 , Calmar - COIN: -0.80 vs. MSTR: -0.67 , Sterling - COIN: -0.86 vs. MSTR: -0.72 , Treynor - COIN: -0.17 vs. MSTR: -0.13 , Ulcer Index - COIN: 48.34% vs. MSTR: 55.20%
Investment Comparison
If you invested $10,000 in each asset on October 7, 2025:
Difference: $67.87 (MSTR ahead)
Coinbase vs MicroStrategy Performance Over Time
| Metric | COIN | MSTR |
|---|---|---|
| 30 Days | 0.6% | 15.2% |
| 90 Days | 16.6% | 75.3% |
| 180 Days | 9.9% | 27.7% |
| 1 Year | -50.6% | -49.9% |
Shorter time frames can show different leaders as market conditions change. Consider your investment horizon when comparing performance.
Coinbase vs MicroStrategy Correlation

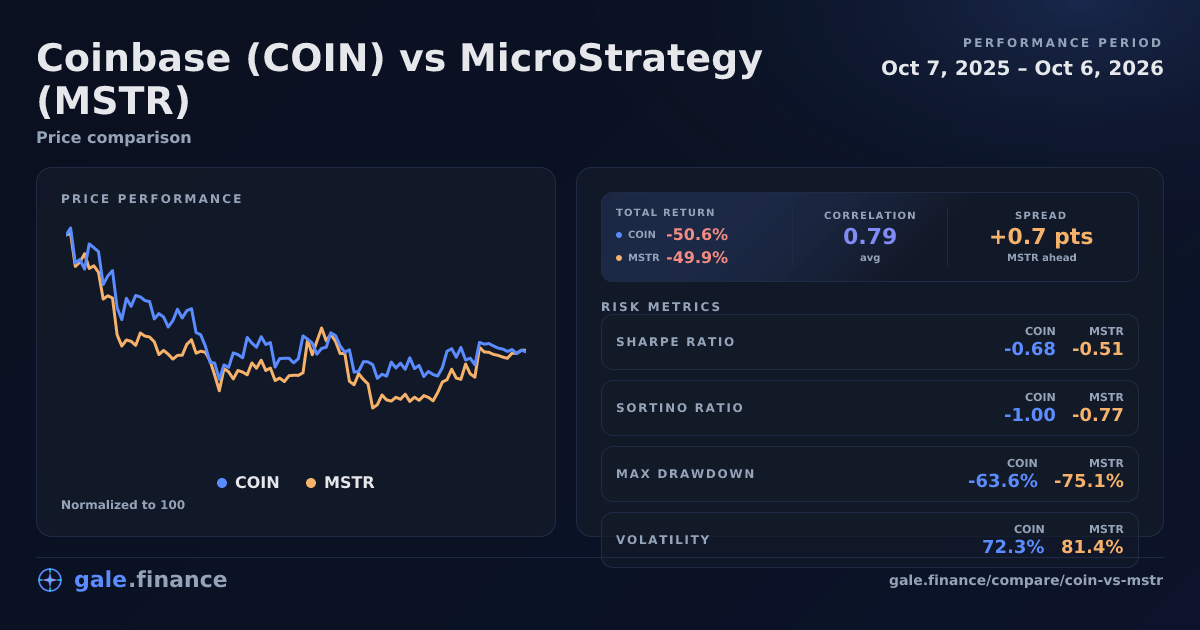
Coinbase and MicroStrategy are strongly correlated over the past year. With a correlation of 0.79, these assets tend to move together, limiting diversification benefits.
For portfolio construction, this strong correlation means holding both COIN and MSTR provides limited risk reduction — they're likely to decline together in downturns.
| Metric | Value |
|---|---|
| Current (30-day) | 0.89 |
| Average (full period) | 0.79 |
| Minimum (30-day rolling) | 0.66 |
| Maximum (30-day rolling) | 0.90 |
Correlation measures how closely two assets move together. Values near +1 indicate strong co-movement, near 0 indicates independence, and negative values indicate inverse movement. Current, minimum, and maximum figures are 30-day rolling correlations on shared daily returns.
Drawdown
Coinbase experienced its maximum drawdown of -63.6% from 2025-10-08 to 2026-02-12. It has not yet recovered to its previous peak.
MicroStrategy experienced its maximum drawdown of -75.1% from 2025-10-08 to 2026-06-26. It has not yet recovered to its previous peak.
Smaller drawdowns and faster recoveries indicate lower downside risk and greater resilience during market stress.
Coinbase vs MicroStrategy Volatility (COIN vs MSTR)
Coinbase's 72.3% annualized volatility translates to about ±4.55% one-standard-deviation daily volatility.
MicroStrategy's 81.4% annualized volatility translates to about ±5.13% one-standard-deviation daily volatility.
MSTR had the wider volatility profile over this window. That means its day-to-day return distribution was broader; COIN was calmer, but lower volatility does not by itself mean better returns.
Treat the ± daily figure as a one-standard-deviation estimate from historical returns, not a forecast or expected absolute daily move. For context, 15-18% annualized volatility is roughly ±1% one-standard-deviation daily volatility.
Risk-adjusted ratios
Sharpe Ratio of COIN and MSTR
Sharpe Ratio: COIN vs. MSTR
Return per total volatilitySharpe gives us excess return per unit of risk. Upside and downside volatility both count as risk.
Sharpe ratio measures return per unit of risk (volatility). A higher Sharpe indicates better risk-adjusted performance. Both Sharpe ratios were negative (MSTR -0.51 vs COIN -0.68), meaning both underperformed the risk-free rate; MSTR was less negative.
A Sharpe above 1.0 is generally considered good, above 2.0 is excellent. Negative Sharpe means the asset underperformed the risk-free rate. Calculated on each asset's full 365-day lookback of available prices and annualized using the asset calendar (365 for crypto, 252 trading days for equities/ETFs/metals).
Sortino Ratio of COIN and MSTR
Sortino Ratio: COIN vs. MSTR
Return per downside volatilitySortino keeps the return-over-risk idea, but only returns below the target rate count as volatility.
Sortino ratio measures return per unit of downside risk. Unlike Sharpe, it only counts downside deviation (returns below the target return). MSTR had better downside-adjusted returns.
A higher Sortino is better. It's useful when upside volatility is common (crypto is the obvious example). Downside deviation: COIN 48.8% vs MSTR 53.4%. Calculated on each asset's full 365-day lookback of available prices, using the daily risk-free rate as the target return, and annualized using the asset calendar (365 for crypto, 252 trading days for equities/ETFs/metals).
Calmar Ratio of COIN and MSTR
Calmar Ratio: COIN vs. MSTR
CAGR per worst drawdownCalmar compares CAGR against the single deepest peak-to-trough loss over the period.
Calmar ratio compares CAGR to maximum drawdown. Higher Calmar means more return per unit of worst drawdown. MSTR posted the higher Calmar ratio.
Calmar is computed on each asset's full 365-day lookback and uses the max drawdown over that same window.
Sterling Ratio of COIN and MSTR
Sterling Ratio: COIN vs. MSTR
Return per average drawdownSterling smooths the drawdown penalty by using average drawdown events instead of only the worst one.
Sterling ratio measures excess return per unit of average drawdown (typically drawdowns worse than 10%). MSTR posted the higher Sterling ratio.
Sterling uses average drawdown events deeper than 10% and subtracts the risk-free rate to report excess return.
Treynor Ratio of COIN and MSTR
Treynor Ratio: COIN vs. MSTR
Excess return per market betaTreynor divides excess annualized return by beta — the sensitivity of the asset to broad-market moves. The slope shown is each asset’s beta vs SPY.
Treynor ratio measures excess return per unit of market risk (beta) instead of total volatility. MSTR posted the higher Treynor ratio.
Treynor uses beta vs the S&P 500 (SPY) on shared dates and the average 3-month Treasury rate as the risk-free rate.
Ulcer Index of COIN and MSTR
Ulcer Index: COIN vs. MSTR
Drawdown painUlcer Index is a risk index, not a return-over-risk ratio. Lower means smaller and shorter drawdowns.
Ulcer Index captures drawdown depth and duration. Lower Ulcer Index means less drawdown pain. COIN had the lower Ulcer Index (less drawdown pain).
Ulcer Index is computed from each asset's drawdown series over the full lookback window.
Tail Risk & Distribution Shape (1-Year): Coinbase vs. MicroStrategy
This section looks at the shape of daily returns, not just the average. Tail stats are computed per asset on its own daily series (crypto includes weekends). We use daily log returns so multi-day moves add cleanly.
Definitions: Value at Risk (VaR), Expected Shortfall, skew, kurtosis, and fat tails.
Tail Risk & Distribution Shape: COIN vs. MSTR (1-Year)
Actual daily return tailsThe bars are real daily log-return observations from the article window. Darker bars are observations at or beyond each asset’s 5% VaR cutoff.
| Metric (1-Year) | COIN | MSTR |
|---|---|---|
| 5% VaR (daily log return) | -7.32% | -7.26% |
| 5% Expected Shortfall (CVaR) | -8.94% (worst 13 days) | -9.50% (worst 13 days) |
| Skew | 0.39 | 0.58 |
| Excess kurtosis | 0.78 | 2.07 |
| 2σ tail days (down / up) | 4 / 10 | 1 / 8 |
| Worst day | -13.34% (2026-02-05) | -17.12% (2026-02-05) |
| Best day | +16.46% (2026-02-13) | +26.11% (2026-02-06) |
Downside co-moves (2σ) — 1-Year
Computed on shared dates only (n=250). A “2σ downside move” means a shared-close log return more than 2 standard deviations below that asset’s own mean on this shared-date series. Dates below show simple returns (%) for readability.
Downside co-move map: COIN vs. MSTR (2σ)
Shared-close daily returnsDots mark actual downside days: asset-colored dots are one-sided downside moves, and red dots are joint downside days. Grey dots add sampled shared-return context when available. The shaded lower-left zone shows where both COIN and MSTR crossed their own 2σ downside threshold.
Show downside tail dates
Dates below are shared-date observations. The “Date” is the period end (close). Tail thresholds are computed on log returns, but the table shows simple returns (%) for readability. Returns are computed from the previous shared close to this one (for example, Friday → Monday includes weekend moves).
Days when both COIN and MSTR had a big down day (2σ)
| Date (interval) | COIN | MSTR |
|---|---|---|
| 2026-02-05 | -13.34% | -17.12% |
Days when COIN had a big down day
| Date (interval) | COIN | MSTR |
|---|---|---|
| 2026-02-05 | -13.34% | -17.12% |
| 2026-03-24 | -9.76% | -1.41% |
| 2026-07-31 | -10.59% | -4.56% |
| 2026-09-15 | -10.10% | -5.36% |
Days when MSTR had a big down day
| Date (interval) | COIN | MSTR |
|---|---|---|
| 2026-02-05 | -13.34% | -17.12% |
Read this as “how ugly the ugly days get”, not as a precise forecast. One-year samples are small, so tail estimates are inherently noisy.
Full Comparison of Coinbase vs. MicroStrategy (1-Year)
| Metric | COIN | MSTR |
|---|---|---|
| Total Return | -50.6% | -49.9% |
| Annualized Volatility | 72.3% | 81.4% |
| Sharpe Ratio | -0.68 | -0.51 |
| Sortino Ratio | -1.00 | -0.77 |
| Calmar Ratio | -0.80 | -0.67 |
| Sterling Ratio | -0.86 | -0.72 |
| Treynor Ratio | -0.17 | -0.13 |
| Ulcer Index | 48.34% | 55.20% |
| Max Drawdown | -63.6% | -75.1% |
| Avg Correlation to S&P 500 | 0.52 | 0.51 |
| 5% VaR (daily log return) | -7.32% | -7.26% |
| 5% Expected Shortfall (CVaR) | -8.94% | -9.50% |
| Skew | 0.39 | 0.58 |
| Excess kurtosis | 0.78 | 2.07 |
| 2σ tail days (down / up) | 4 / 10 | 1 / 8 |
Audit this calculation
Formulas, inputs, and conventions used to compute the metrics on this page.
Inputs & conventions
- Shared window for pair metrics
- 2025-10-07 → 2026-10-06 (last shared close).
- Rolling correlation sample (shared closes)
- 221 rolling 30-day values (from 250 shared daily returns).
- Annualization (days/year)
- COIN: 252 days/year; MSTR: 252 days/year.
- Risk-free rate
- Uses the 3-month U.S. Treasury yield (FRED: DGS3MO), averaged over each asset’s window:
- COIN: 3.81% over 2025-10-07 → 2026-10-06.
- MSTR: 3.81% over 2025-10-07 → 2026-10-06.
- Volatility drag (rule of thumb)
- Estimated from annualized volatility (simple returns). For the log-return framing, see Log returns.
- COIN: ≈ -26.1%/yr
- MSTR: ≈ -33.1%/yr
- Data alignment
- No forward fill. Correlation and tail co-moves are computed on shared closes only. For cross-calendar pairs (e.g., crypto vs stocks), weekend/holiday moves roll into the next shared close.
- Return conventions
- Volatility/Sharpe/Sortino use simple daily returns. Tail-risk uses daily log returns for distribution stats (but tables show simple returns). Log returns.
Formulas
- Price on day t.
- Simple daily return.
- Log daily return.
- Average daily return.
- Standard deviation of daily returns.
- Annualization factor (days/year).
- Annual risk-free rate.
Coinbase vs MicroStrategy: Frequently Asked Questions
Which has higher volatility: COIN or MSTR?
MSTR showed higher volatility at 81.4% annualized, compared to 72.3% for COIN Over the past year. Higher volatility means larger price swings in both directions.
Does COIN provide diversification when held with MSTR?
COIN and MSTR are strongly correlated over the past year, with an average correlation of 0.79. This strong correlation limits diversification benefits.
How bad are the worst 5% days for COIN vs MSTR?
Over the past year, COIN's 5% VaR was -7.32% and its 5% Expected Shortfall was -8.94% (worst 13 days). MSTR's were -7.26% and -9.50% (worst 13 days).
Do COIN and MSTR crash together on bad days?
On shared dates (n=250), when MSTR has a 2σ down day, COIN also does 100.0% (1/1 days). In the other direction, when COIN has one, MSTR also does 25.0% (1/4 days).
Which has better risk-adjusted returns: COIN or MSTR?
Both assets posted negative Sharpe ratios Over the past year (MSTR -0.51 vs COIN -0.68), meaning both underperformed the risk-free rate; MSTR was less negative.
Can COIN and MSTR be combined in a portfolio?
Yes, though allocation sizing matters. Their strong correlation provides limited risk reduction since they tend to move together. MSTR's higher volatility (81.4%) means even small allocations can materially impact overall portfolio risk.